Casino self-exclusion gives players a practical way to stop gambling when they need a break or want to regain control of their spending. However, closing access to a casino account involves more than simply logging out. Players must also understand how casino self-exclusion affects debit card payments, recurring authorisations and other funding methods.
Debit cards make online casino deposits convenient. Nevertheless, that convenience can create difficulties for someone trying to stop gambling. Saved card details, payment permissions and previously approved transactions may require additional attention after an exclusion request.
Fortunately, licensed gambling operators generally have procedures that restrict account activity once self-exclusion takes effect. These measures aim to prevent players from depositing funds, placing bets or accessing gambling services during their exclusion period.
For players researching payment options, understanding how Mastercard Debit Card Casinos handle deposits also provides useful context. Payment convenience should always come with clear spending controls and responsible gambling protections.
How Casino Self-Exclusion Restricts New Card Transactions
Self-exclusion is a formal request that prevents someone from accessing gambling services for a selected period or, depending on the operator, indefinitely. Once the request becomes effective, the casino should restrict the player’s account according to its licensing obligations and exclusion procedures.
Importantly, these restrictions should cover more than gameplay.
Blocking New Debit Card Deposits
When an operator activates self-exclusion, the account should no longer accept new gambling deposits. Consequently, players should not be able to use previously saved debit card details to fund their casino balances.
The payment system and account management platform usually work together to enforce this restriction. The casino may disable deposit buttons, suspend payment permissions and flag the account against further transactions.
However, the exact implementation varies between operators and jurisdictions.
For example, some platforms apply restrictions immediately after processing an exclusion request. Others may require a short administrative period before the account status changes. Players should therefore request confirmation rather than assume that submitting a form automatically blocks every transaction.
Preventing Access Through Existing Accounts
Self-exclusion should also prevent players from bypassing restrictions through the same operator’s other services where applicable.
For instance, a gambling company might operate several casino brands under one licence. Depending on local regulations and the exclusion system, the restriction may extend across those brands.
This matters because switching between platforms operated by the same company should not become an easy way around a responsible gambling decision.
Moreover, operators should maintain appropriate records of exclusion requests and apply relevant account restrictions consistently.
Casino Self-Exclusion and Existing Deposit Authorisations
One important issue deserves particular attention: existing payment authorisations.
A player might have saved debit card information, approved recurring transactions or previously authorised payment arrangements before requesting self-exclusion. Although the casino should restrict new deposits, these existing permissions can create questions about outstanding transactions.
Do Saved Debit Cards Continue Processing Payments?
Saving a debit card makes future deposits easier because players do not need to enter their details repeatedly. However, storing payment information does not automatically mean that every future transaction has permanent authorisation.
Most standard casino deposits involve individual payment requests. The operator submits a transaction through its payment processor, and the bank approves or declines it.
After self-exclusion takes effect, the operator should prevent new gambling deposits from being initiated through the restricted account.
Nevertheless, players should check whether any transactions remain pending. A payment submitted before the exclusion became active might still appear in the banking system afterwards.
Therefore, distinguish between a new deposit and the later settlement of an earlier transaction.
What Happens to Recurring Deposit Authorisations?
Recurring payment arrangements require additional attention.
Some payment services support stored credentials or merchant-initiated transactions. These arrangements can allow eligible merchants to process subsequent payments under an existing agreement.
However, ordinary debit card casino deposits do not necessarily operate this way. Players should not assume that every saved card creates an automatic recurring payment.
If an operator has an active recurring arrangement, the player should request its cancellation alongside self-exclusion.
The following steps can help:
-
Contact the casino’s payment department.
-
Request cancellation of recurring deposit permissions.
-
Ask the operator to remove or disable stored payment credentials.
-
Check pending transactions with the bank.
-
Review the next bank statement for unexpected gambling-related charges.
Additionally, request written confirmation that the operator has disabled future payment activity.
This provides a useful record if a disputed transaction appears later.
Bank-Level Gambling Merchant Blocking Options
Although casino self-exclusion restricts activity at the operator level, players can strengthen their protection through their banks.
Many financial institutions offer gambling merchant blocking services. These controls can prevent eligible debit card transactions to gambling businesses, adding another barrier against unwanted deposits.
How Bank Gambling Blocks Work
Banks use merchant category codes (MCCs) and other transaction information to identify different types of businesses.
Gambling merchants commonly use specific merchant category classifications when processing card payments. A bank with gambling transaction controls can use these classifications to identify and decline eligible transactions.
For example, a player might activate a gambling block through their banking application. When they subsequently attempt to deposit money at a supported gambling merchant, the bank may decline the payment.
This approach provides an additional safeguard because it operates independently of the casino account.
However, coverage varies between banks and payment networks. Some gambling transactions might not be identified correctly, particularly when payment intermediaries or alternative processing arrangements are involved.
Therefore, a bank-level block should complement self-exclusion rather than replace it.
Activating Gambling Blocks Through Banking Applications
Many banks now provide digital tools that allow customers to manage card security and spending restrictions.
Depending on the institution, players may find gambling controls under card settings, transaction management or merchant restrictions.
The activation process generally involves:
-
Opening the bank’s mobile application.
-
Accessing debit card or spending controls.
-
Looking for gambling transaction restrictions.
-
Activating the available blocking option.
-
Confirming that the restriction applies to the relevant card.
Some institutions require customers to contact customer support instead.
Additionally, players should ask whether the block covers online gambling, international transactions and payments processed through third-party providers.
Comparing Casino Exclusion With Bank-Level Payment Controls
Casino self-exclusion and bank-level gambling blocks serve related but different purposes.
The casino restriction prevents access to gambling services through the operator. Meanwhile, the bank restriction targets eligible financial transactions.
Using both measures can provide stronger protection.
| Protection method | Main purpose | Important limitation |
|---|---|---|
| Casino self-exclusion | Restricts account access and gambling activity | Applies according to operator and regulatory coverage |
| Debit card blocking | Prevents eligible gambling card payments | Merchant identification may vary |
| Recurring payment cancellation | Stops authorised repeat transactions | Existing pending payments may still settle |
| Card replacement | Changes compromised or unwanted card credentials | Does not necessarily block future gambling payments |
| Spending limits | Controls eligible card expenditure | May not prevent every gambling transaction |
For example, someone who excludes themselves from one casino might still encounter gambling advertisements or discover another operator.
A bank-level block can help prevent impulsive deposits across participating merchants. Nevertheless, players should check whether the restriction covers all relevant payment channels.
Moreover, replacing a debit card alone is not a reliable self-exclusion strategy. Some stored payment arrangements may use account updater services or other mechanisms to maintain merchant credentials.
What Happens to Pending Deposits and Casino Withdrawals?
Self-exclusion does not automatically resolve every outstanding financial transaction.
Players may have pending deposits, unsettled card payments or remaining casino balances when they request exclusion. These situations require careful handling.
Handling Deposits Submitted Before Exclusion
Suppose a player submits a debit card deposit shortly before activating self-exclusion.
The casino might already have sent the transaction for processing. Consequently, the payment could appear in the bank account after the exclusion request.
This does not necessarily mean the operator accepted a new deposit after exclusion.
Players should contact both the casino and their bank if they notice an unexpected transaction. They should provide the transaction date, amount and reference number.
Furthermore, they should avoid making additional deposits while waiting for clarification.
Requesting Withdrawals During Self-Exclusion
Self-exclusion generally restricts gambling activity, not legitimate access to funds already owed to a player.
Therefore, operators should explain how customers can request eligible withdrawals without reopening gambling access.
Depending on the operator’s procedures, identity verification and payment checks may still apply.
Players should ask about withdrawal processing, outstanding balances and any documentation requirements. They should also avoid creating another account simply to access existing funds.
Importantly, exclusion should remain active throughout the financial resolution process.
Practical Steps for Strengthening Debit Card Protection
Responsible gambling protection works best when players combine several safeguards.
Although self-exclusion provides an important starting point, additional financial controls can help reduce the risk of returning to unwanted gambling activity.
Consider these practical measures:
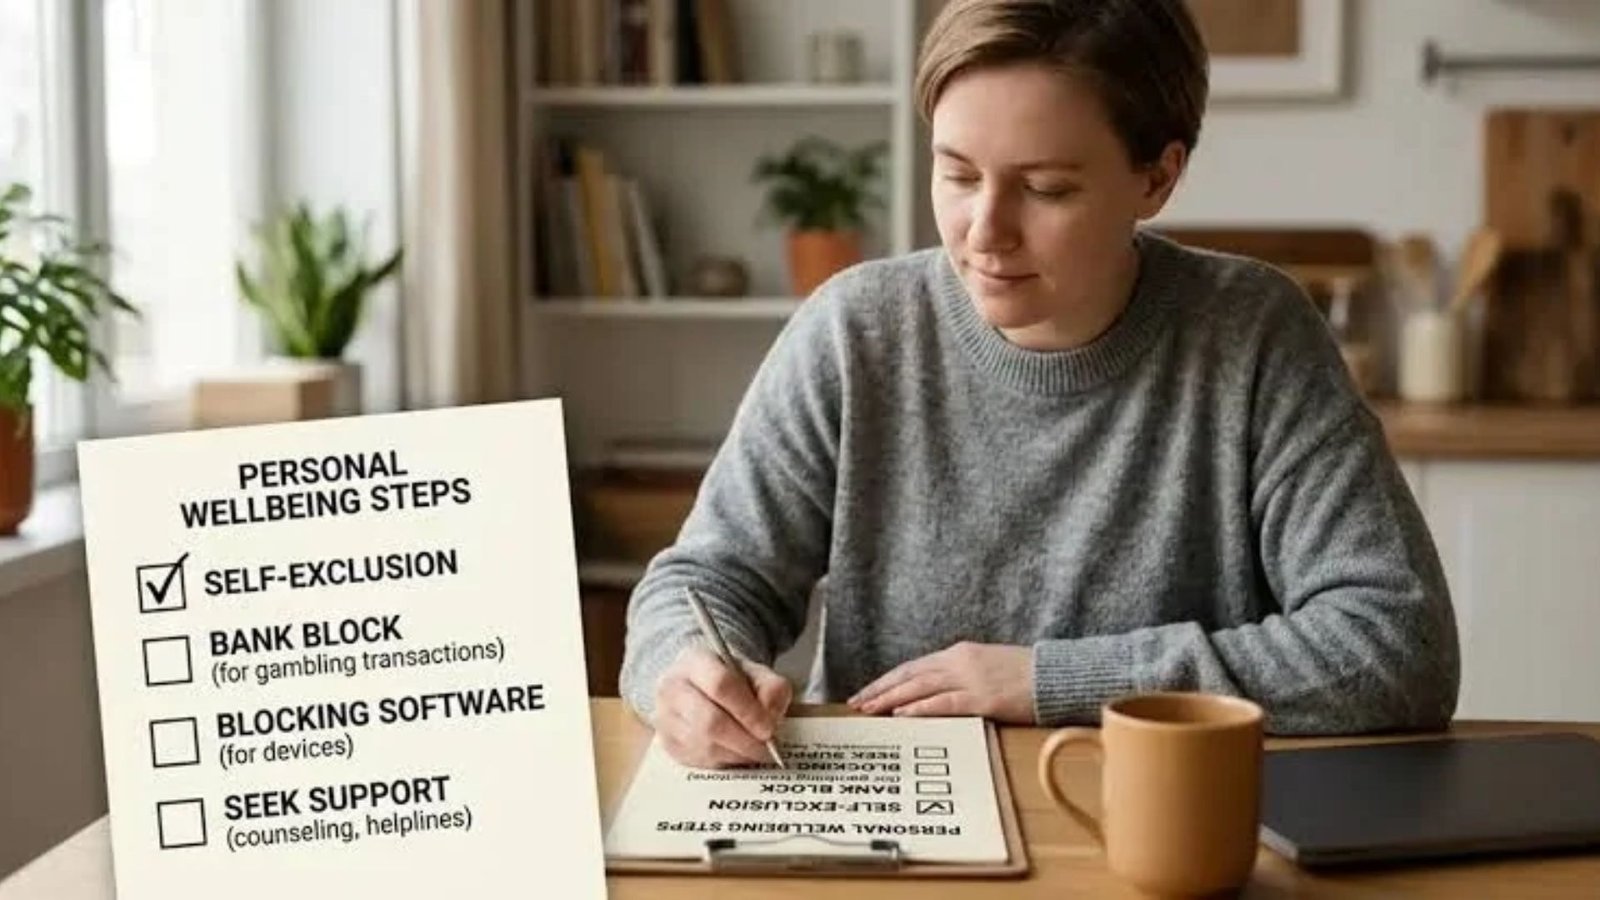
1. Activate formal self-exclusion. Contact the casino directly and request an appropriate exclusion period. Keep confirmation of the request.
2. Cancel stored payment permissions. Ask the operator to disable saved cards and any recurring deposit arrangements.
3. Contact your bank. Find out whether it offers gambling merchant blocking for debit card transactions.
4. Review transaction activity. Monitor your statements for unexpected payments and investigate unfamiliar gambling-related charges.
5. Remove saved card details. Delete stored payment information from gambling accounts and other relevant services where possible.
6. Avoid alternative funding routes. Consider whether e-wallets, bank transfers or other payment methods could undermine the financial restrictions you have introduced.
7. Seek additional support. If gambling urges remain difficult to manage, consider professional support or an appropriate gambling helpline.
These steps create several layers of protection. More importantly, they reduce reliance on willpower alone.
Common Mistakes When Using Casino Self-Exclusion
Even when players make a genuine commitment to stop gambling, certain misunderstandings can weaken their protection.
One common mistake involves assuming that closing a casino account automatically blocks every payment connected to it. In reality, players should confirm that the operator has activated the exclusion and addressed outstanding payment permissions.
Another mistake is relying exclusively on a bank gambling block. While useful, these controls may not identify every transaction involving gambling-related services.
Additionally, some players assume that replacing a debit card will prevent all future gambling payments. However, card replacement does not necessarily cancel merchant agreements or prevent transactions through alternative funding methods.
Finally, players sometimes create accounts with other operators during an exclusion period. This defeats the purpose of the original decision and can introduce further financial difficulties.
Instead, use the exclusion period to establish stronger boundaries and seek support where necessary.
The Role of Responsible Gambling Protections in 2026
The online gambling industry continues to develop its payment security and responsible gambling systems.
In 2026, operators face increasing expectations around customer protection, account monitoring and safer payment practices. Regulators in different jurisdictions also continue to refine requirements for self-exclusion and customer safeguards.
Payment providers are an important part of this development.
Banks can strengthen customer protection through gambling transaction controls, while casino operators can improve exclusion management and payment restrictions.
Nevertheless, implementation remains inconsistent across markets. A feature available through one bank or licensed casino might not exist elsewhere.
Consequently, players should verify the protections offered by their specific financial institution and gambling operator.
The most effective approach combines clear exclusion procedures, reliable payment restrictions and accessible support services.
Final Thoughts: Making Debit Card Payments Safer Through Self-Exclusion
Casino self-exclusion provides an important safeguard for anyone who wants to stop gambling. However, protecting that decision requires attention to both casino accounts and financial arrangements.
Operators should restrict new debit card deposits once exclusion becomes effective. They should also address saved payment credentials and any applicable recurring authorisations.
Meanwhile, bank-level gambling merchant blocks can provide an additional layer of protection against unwanted transactions.
Ultimately, no single measure guarantees complete protection. Players should combine formal self-exclusion, banking controls, transaction monitoring and appropriate support.
Most importantly, self-exclusion should represent a meaningful opportunity to step away from gambling without unnecessary financial pressure.